

Kenya’s listed banks grew their core earnings per share by 16.3 percent in the first half of 2026, nearly double the 8.4 percent pace recorded a year earlier, according to Cytonn Investments’ H1’2026 Banking Sector Report. The improvement came alongside a sharp drop in bad loans, positioning the sector for its best half year performance since the current interest rate cycle began.
The report, titled “Digital Momentum and Improving Asset Quality,” reviews all 11 banks listed on the Nairobi Securities Exchange and marks the first comprehensive comparison of their H1’2026 results against a common set of metrics, filling a gap left by the individual earnings releases each bank published earlier this year.
Bad Loans Ratio Falls as Recoveries Pick Up
The market weighted average non performing loan ratio dropped to 11.1 percent in H1’2026 from 13.8 percent in H1’2025, a swing of 2.7 percentage points. Every bank except Family Bank posted an improvement, with Equity Group cutting its NPL ratio by 5 percentage points to 10.2 percent, the largest single move in the sector.
| Bank | H1’2026 NPL Ratio | H1’2025 NPL Ratio | Change |
|---|---|---|---|
| Equity Group | 10.2% | 15.3% | -5.0 pts |
| KCB Group | 14.5% | 17.9% | -3.3 pts |
| Co-operative Bank | 14.2% | 17.3% | -3.1 pts |
| Absa Bank Kenya | 10.2% | 13.2% | -3.0 pts |
| HFCB Group | 21.4% | 24.0% | -2.7 pts |
| I&M Group | 8.4% | 11.0% | -2.5 pts |
| Stanbic Holdings | 7.3% | 9.5% | -2.1 pts |
| NCBA Group | 10.8% | 12.2% | -1.4 pts |
| Standard Chartered | 5.1% | 6.0% | -0.9 pts |
| Diamond Trust Bank | 12.2% | 12.9% | -0.7 pts |
| Family Bank | 14.7% | 13.5% | +1.2 pts |
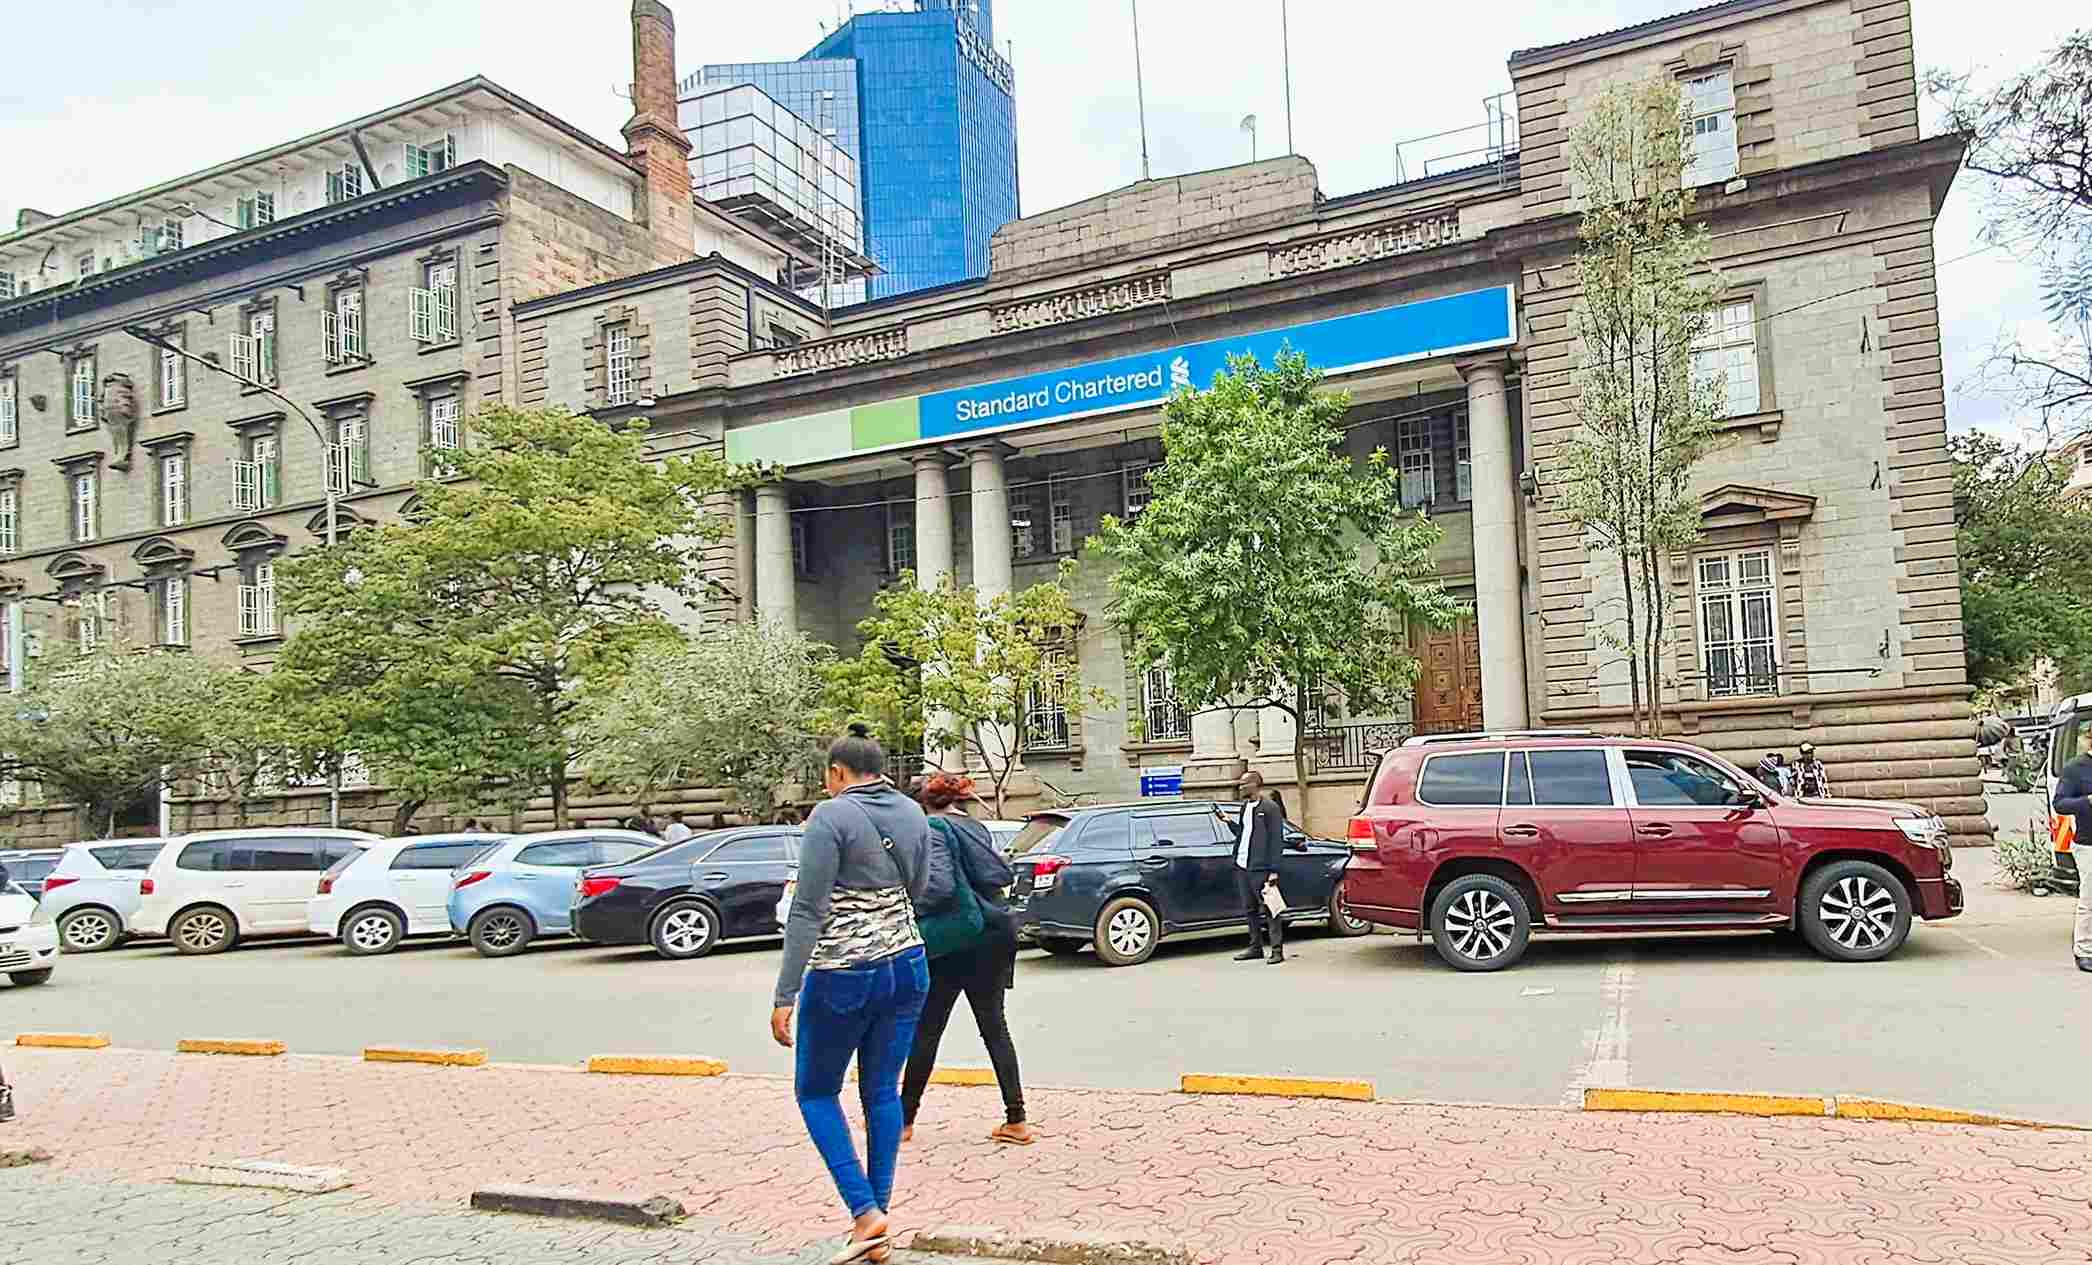
Standard Chartered Bank Kenya kept the cleanest book in the sector at 5.1 percent, extending a pattern the lender has held for several review periods.
Which Banks Grew Fastest
HFCB Group led earnings growth with core EPS up 59.9 percent, followed by Diamond Trust Bank at 35.8 percent and Equity Group at 31.5 percent. Standard Chartered posted the only decline among the eleven, with core EPS down 16.8 percent as interest income fell 17.5 percent.
| Bank | Core EPS Growth | Net Interest Income Growth | Return on Average Equity |
|---|---|---|---|
| HFCB Group | 59.9% | 29.4% | 10.3% |
| Diamond Trust Bank | 35.8% | 26.4% | 13.1% |
| Equity Group | 31.5% | 16.8% | 29.1% |
| Co-operative Bank | 28.0% | 13.0% | 20.6% |
| Family Bank | 27.0% | 40.7% | 23.3% |
| I&M Group | 22.4% | 22.5% | 18.0% |
| KCB Group | 14.5% | 7.0% | 22.0% |
| NCBA Group | 12.2% | 20.4% | 19.8% |
| Stanbic Group | 1.3% | 5.5% | 20.7% |
| Absa Bank Kenya | -9.8% | -5.4% | 23.3% |
| Standard Chartered | -16.8% | -19.8% | 17.1% |

Cytonn attributes the sector-wide gain mainly to non-funded income, which grew 14.6 percent against a 5.8 percent decline in H1’2025. Fees and commissions income climbed to 14.4 percent growth from 4.2 percent, a sign banks leaned harder on transaction and digital channels rather than interest margins to drive profit.
Co-operative Bank’s own H1’2026 statement echoed the trend, with the lender’s management crediting proactive credit management for the improvement: it continued to strengthen asset quality through proactive credit management, customer engagement and portfolio monitoring.
Bank Shares Still Trade Below Historical Value
Despite the earnings recovery, the sector trades cheap. Listed banks carry an average price to tangible book value of 1.3x and an average price to earnings ratio of 6.0x, below the 21 year historical average of 1.4x for price to book.
| Bank | Market Cap (KSh bn) | P/E | P/TBV |
|---|---|---|---|
| Standard Chartered | 125.0 | 11.3x | 2.2x |
| HFCB Group | 21.5 | 12.0x | 1.2x |
| Stanbic Bank | 109.9 | 8.0x | 1.6x |
| Absa Bank | 168.9 | 7.8x | 1.8x |
| Family Bank | 46.5 | 6.8x | 1.4x |
| I&M Holdings | 139.6 | 6.4x | 1.2x |
| Co-op Bank | 204.2 | 6.1x | 1.2x |
| NCBA Group | 142.1 | 5.7x | 1.1x |
| Diamond Trust Bank | 50.2 | 4.0x | 0.5x |
| Equity Bank | 371.7 | 4.3x | 1.2x |
| KCB Group | 279.6 | 3.8x | 0.8x |

Prices reflect the market close on September 18, 2026. Cytonn’s valuation model gives KCB Group the highest total potential return in the sector at 38.4 percent, combining a 30.3 percent price upside to its KSh113.40 target with an 8.0 percent dividend yield. Co-operative Bank follows at 33.0 percent, and Standard Chartered ranks last among the eleven at 16.2 percent despite carrying the sector’s richest valuation multiples.
On franchise value, which weighs profitability, efficiency, liquidity and asset quality together, Equity Bank ranks first, driven by a 29.1 percent return on average equity against a market weighted average of 22.2 percent. KCB Group ranks second and Co-operative Bank third.
Rate Cuts Slow as Middle East Tensions Weigh on the Outlook
The earnings gains came against a more cautious monetary policy stance. The Central Bank of Kenya’s Monetary Policy Committee cut the benchmark rate once in H1’2026, by 25 basis points to 8.75 percent, then held it there through August as officials watched oil prices tied to the ongoing Middle East conflict. Inflation averaged 6.2 percent in the second quarter, up from 3.9 percent a year earlier, driven largely by fuel costs.
Private sector credit growth strengthened even so, rising to 10.2 percent in July from 3.3 percent a year earlier as lower lending rates worked through the system. The Kenya shilling held broadly steady, slipping 36 basis points against the dollar to close the half at KSh129.5, while the current account deficit widened to 3.0 percent of GDP from 1.9 percent a year earlier.
Context From Kenya’s Banking Cycle
Cytonn has published this review each quarter since at least 2018, and its findings have tracked the sector’s swings between stress and recovery. In its Q3’2018 report, Khusoko covered a period when operating efficiency was improving even as bad loans climbed, the mirror image of the current half, where efficiency has held steady while asset quality improved.
A 2023 review covered by Khusoko tracked KCB Group overtaking Equity as Kenya’s largest bank by assets, a lead the H1’2026 figures show it has extended, with KCB’s loan book now the largest in the eleven bank set alongside the highest projected total return.
The H1’2026 figures suggest the sector has moved past the asset quality strain that defined much of the past three years, with digital income and disciplined credit management doing more of the work that interest margins once carried. Whether that holds depends largely on factors outside any bank’s control: fuel prices, the shilling, and how long the Middle East conflict keeps the Central Bank in a holding pattern.
