

Kenya’s fixed internet market grew faster than any other segment tracked by the Communications Authority of Kenya in the 2025/26 financial year, with subscriptions rising 32.4 per cent to 2.84 million by the end of June 2026, up from 2.14 million a year earlier.
CA called the segment a case of “unprecedented growth, driven by intense competition, a shifting digital economy, and aggressive infrastructure rollouts” in its fourth quarter report. Quarter on quarter growth alone came in at 6.9 per cent between March and June.
Technology shift favors fibre and wireless
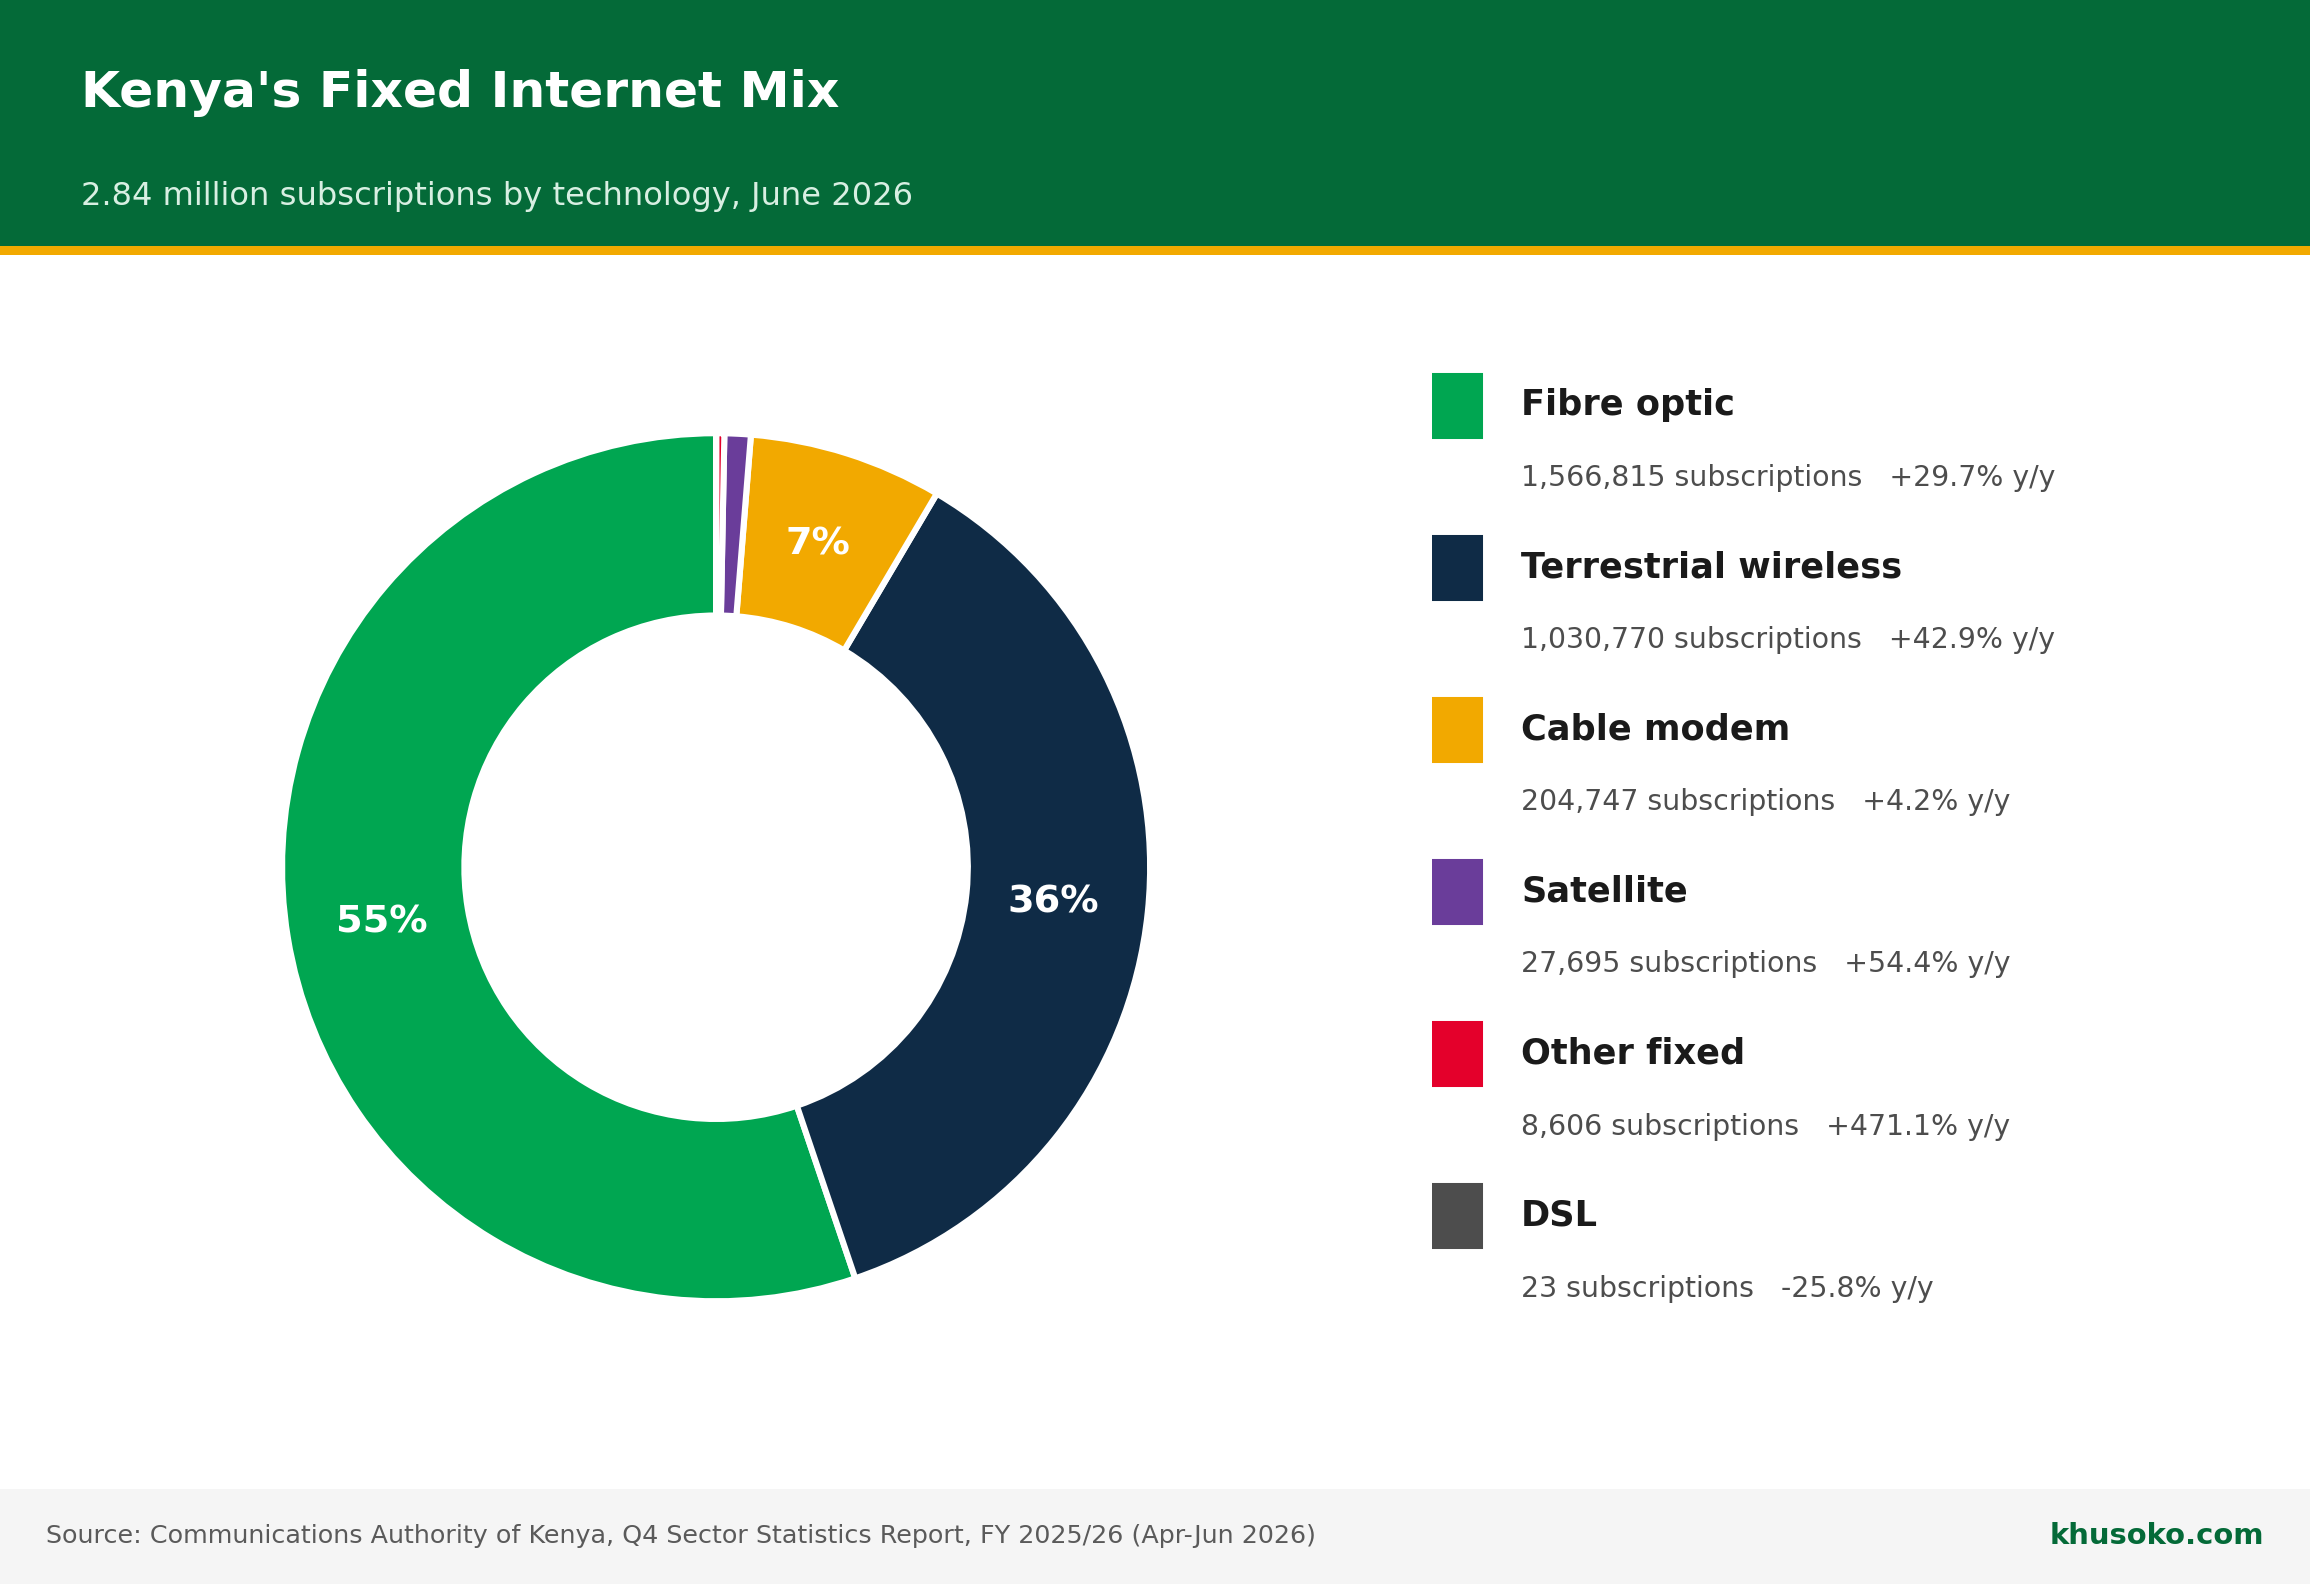
Fibre optic connections remain the backbone of the market, growing 29.7 per cent year on year to 1.57 million subscriptions. Terrestrial wireless technology grew even faster, up 42.9 per cent to just over 1.03 million connections, an expansion that mirrors Airtel’s own 5G home broadband push, which alone added hundreds of new sites across 39 counties.
Satellite subscriptions climbed 54.4 per cent to 27,695. The steepest jump came from a small base: other fixed technologies, mainly radio links rolled out by Airtel, Jamii Telecommunications and Fiberlink, grew 471.1 per cent year on year. DSL kept declining, dropping another 25.8 per cent to just 23 active lines nationwide.
| Technology | Jun 2026 subscriptions | Year on year change |
|---|---|---|
| Fibre optic | 1,566,815 | +29.7% |
| Terrestrial wireless | 1,030,770 | +42.9% |
| Cable modem | 204,747 | +4.2% |
| Satellite | 27,695 | +54.4% |
| Other fixed | 8,606 | +471.1% |
| DSL (copper) | 23 | -25.8% |
| Total | 2,838,656 | +32.4% |
Safaricom crosses a million, but barely moves its share
Safaricom PLC crossed one million fixed data subscriptions for the first time in June 2026, closing the quarter at 1,024,950 connections. Its market share, however, sits at 36.1 per cent, down from the 46.1 per cent it held in 2023, when Khusoko first tracked the operator’s dominance of a much smaller market.
The gap points to a strategy built on volume rather than share defence: Safaricom has leaned on its wider mobile business, where it controls the overwhelming majority of Kenya’s mobile subscriptions, to grow fixed broadband through bundling rather than fibre pricing power. Products like Family Share tie home broadband to mobile data, voice and SMS, making switching networks costlier for customers even as Safaricom’s outright fixed-data lead narrows.
That volume push has come at a margin cost, and Khusoko has tracked the trade-off directly: in April 2026, Safaricom doubled fibre speeds across most residential plans without raising prices, then quietly cut Fair Usage Policy data caps by as much as 90 per cent in the same update — reversing a 15TB threshold it had introduced only five months earlier. The 40 Mbps Bronze plan’s cap fell to 1.5TB, meaning faster connections now hit the throttling wall sooner than the slower plans they replaced.
Jamii Telecommunications, whose Faiba network posted faster average speeds than Safaricom in independent tests over the year to March 2026, still imposes no fair usage cap at all, an advantage that helps explain why Jamii holds the second-largest share at 19.1 per cent.

Wananchi Group’s 10.4 per cent share also comes with fresh capital behind it: AXIAN Telecom’s acquisition of a 99.63 per cent stake in Wananchi, the parent of Zuku and Simbanet, was backed by IFC financing and gives the operator room to expand its network. Poa Internet, by contrast, has felt the squeeze of Safaricom’s own budget-tier push into peri-urban estates, with its share falling to 8.8 per cent after four consecutive quarters of decline.
Even a well-capitalised entrant has struggled against Safaricom’s scale: Airtel wound down its wholesale fibre subsidiary, Telesonic, in September after two years without generating commercial revenue, unable to compete for a corporate customer base that Safaricom and its peers had already locked up.
| Operator | Subscriptions | Market share |
|---|---|---|
| Safaricom PLC | 1,024,950 | 36.1% |
| Jamii Telecommunications | 541,003 | 19.1% |
| Wananchi Group (Kenya) | 294,375 | 10.4% |
| Ahadi Wireless | 270,586 | 9.5% |
| Poa Internet Kenya | 248,601 | 8.8% |
| Vilcom Network | 186,240 | 6.6% |
| Mawingu Networks | 105,275 | 3.7% |
| Vijiji Connect | 35,861 | 1.3% |
| Starlink Internet Services Kenya | 27,616 | 1.0% |
| Dimension Data Solutions | 23,280 | 0.8% |
Starlink Internet Services Kenya, the satellite provider linked to Elon Musk’s SpaceX, held a 1.0 per cent share with 27,616 subscriptions, still small but notable in a category CA says is shifting away from older VSAT satellite technology toward low earth orbit networks.
Total available satellite bandwidth capacity in the country fell 19.1 per cent year on year even as utilized capacity grew, a sign that legacy satellite links are being retired faster than new ones come online.
Bandwidth keeps pace
Kenya’s total available international internet bandwidth reached 28,950 gigabits per second by June 2026, up 18.5 per cent year on year, while utilized capacity grew 23.9 per cent.
Submarine cable systems including SEACOM, TEAMS, EASSy, PEACE and DARE 1 carry most of that traffic, with SEACOM accounting for the largest single share.
The takeaway
Fixed internet is the one corner of Kenya’s telecom market where Safaricom’s usual scale advantage does not automatically translate into dominance. With fibre, wireless and satellite technologies all expanding and at least ten operators holding meaningful share, the segment offers Kenyan households and businesses more genuine choice than the mobile market a few kilometers away.
