
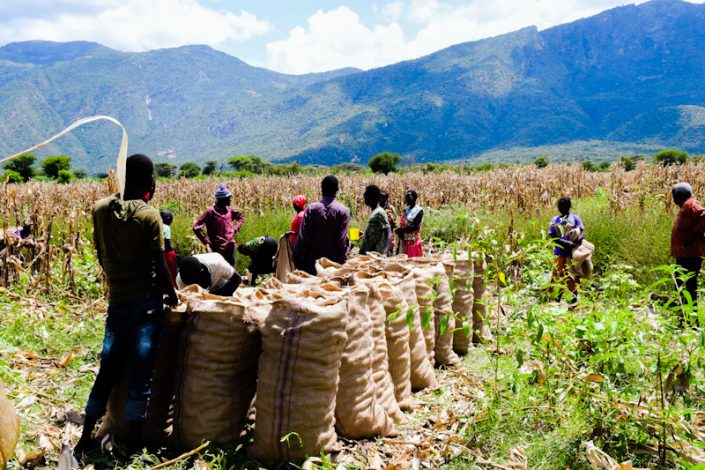
Kenya’s maize harvest has taken its steepest hit in years. The United States Department of Agriculture has cut its forecast for the 2026/27 marketing year by 51 percent, down to 2.2 million metric tons, after a dry spell scorched the country’s main grain counties between June and July.
The shortfall forces the government into a difficult calculation. To keep maize meal and bread supplies steady, Kenya now needs to import a record 2.3 million metric tons of corn, according to the latest Grain and Feed report from the USDA’s Foreign Agricultural Service in Nairobi, dated August 28.
Wheat has fared no better. The forecast for that crop dropped by more than half, to 130,000 tons, hit by the same drought that swept through the Rift Valley’s wheat belt. Rice stands out as the one crop holding steady, with irrigation at the Mwea scheme keeping milled output near 225,000 tons, though the country will still need to import 750,000 tons to close the gap between what it grows and what it eats.
How the drought hit Kenya’s grain belt
Rainfall across western Kenya fell to its lowest level since 1980. In parts of the region, monthly rainfall ran more than 200 millimeters below normal through June and July. Rain returned in late July, but by then standing crops had already failed.
Uasin Gishu, Trans Nzoia and Nakuru, the counties that usually produce a surplus for the rest of the country, recorded some of the worst losses. USDA field staff who visited the North Rift and western regions in late July found close to half the planted area wiped out, with surviving fields expected to yield up to 35 percent less than usual.
Farmers now face a harder choice than usual: replant into uncertain weather, or wait and risk missing the season entirely.
“Farmers are not sure whether to plant or wait until the next season.” — Kipkorir Menjo, Director, Kenya Farmers Association, via Daily Nation.
Satellite data cited in the USDA report traces the worst crop failure through a band running from West Pokot and Trans Nzoia down through Uasin Gishu, Kericho and Narok. Eastern and central Kenya, which rely more on short rains, largely escaped this round of losses.
Kenya’s 2026/27 grain outlook: original forecast versus revised
| Crop | Original forecast | Revised forecast | Change | Imports needed |
|---|---|---|---|---|
| Maize | 4.5 million MT | 2.2 million MT | down 51% | 2.3 million MT |
| Wheat | 280,000 MT | 130,000 MT | down 54% | 2.6 million MT |
| Rice, milled | 180,000 MT | 225,000 MT | up 25%* | 750,000 MT |
*Rice forecast raised on added irrigated acreage, holding steady against the government’s earlier estimate. Source: USDA Foreign Agricultural Service, Nairobi, Report KE2026-0017.
Where Kenya could find replacement corn
The government has signalled it will import, but the supply lines are not yet fixed, and Kenya’s usual regional partners are stretched thin this season. Uganda’s harvest has slipped after its own weather troubles, and Tanzania’s exportable surplus has narrowed to roughly 800,000 tons, far short of what Kenya now needs. Zambia is the exception, sitting on a bumper harvest that leaves it with a net exportable surplus near 1.47 million tons, though the USDA warns that an approaching El Nino season could trim Zambia’s own outlook for the next planting cycle.
Potential corn suppliers for Kenya, 2026/27
| Country | Forecast exports (million MT) | Notes |
|---|---|---|
| Zambia | 0.60 | Non GM white corn, duty free access, strong harvest |
| Tanzania | 0.70 | Non GM white corn, duty free, limited by permits |
| South Africa | 2.50 | Non GM supply available, volume limited by screening |
| Uganda | 0.30 | Non GM white corn, duty free, output down this season |
| United States | 83.19 | Mostly GM yellow corn, 50 percent tariff applies |
| Brazil | 43.00 | Mostly GM yellow corn, 50 percent tariff applies |
| Argentina | 40.00 | Mostly GM yellow corn, 50 percent tariff applies |
Source: USDA Foreign Agricultural Service, Nairobi, Report KE2026-0017.
Kenya’s ban on genetically modified imports rules out cheap corn from Argentina, Brazil and the United States, all of which also face steep tariffs on entry into the Kenyan market. South Africa can supply non GM white and yellow corn, but its surplus is small next to the size of Kenya’s gap.
Officials have floated a duty free window allowing in up to three million tons of white corn, alongside a separate allocation of 360,000 tons of yellow corn set aside for animal feed. The goal is to keep white corn on household plates while pushing feed millers toward the yellow variety instead.
Wheat gap unlikely to close quickly
Kenya’s wheat shortfall is smaller in volume but harder to fix on short notice. Harvested area is expected to fall to 70,000 hectares from a prior estimate of 100,000, and yields are projected to drop to 1.8 tons per hectare, a decline of nearly 36 percent from the original forecast. Millers are also bracing for weaker grain quality, with low test weights and shrunken kernels expected from crops that never finished developing.
Domestic wheat has historically covered less than 15 percent of Kenya’s needs even in good years, so heavy imports were always part of the picture. What has changed is scale, with the USDA now projecting 2.6 million tons of wheat imports this year. Kenyan millers typically draw on the Black Sea region, Argentina and Australia, and a new requirement for destination inspection on US wheat adds friction to that route at a time when speed matters most.
El Nino threatens a swing from drought to floods
Just as Kenya works out how to plug this year’s shortfall, forecasters are watching a different threat build. An emerging El Nino, paired with a strongly positive Indian Ocean Dipole, carries an 80 to 82 percent probability of pushing the region into an intense, wet season by October, according to the USDA report. Kenyan meteorologists have compared the setup to the pattern that preceded the East African floods of 1997.
That shift from dry to wet ground carries its own risks. Flash floods could wash away newly planted crops, and grain that is harvested may not dry properly, raising the risk of spoilage after harvest. The short rain areas of eastern and central Kenya, largely spared by this year’s drought, are expected to feel the El Nino impact most.
What it means for households and millers
For consumers, the effect shows up first at the market stall. Local corn prices have already climbed past 50,000 shillings, roughly 388 dollars, per metric ton at buying centers. The Cereal Millers Association has described this season’s decline as among the steepest in years, with only a handful of counties expected to produce more than a million bags of maize.
The feed sector faces its own pressure. Because Kenya’s GMO ban limits access to cheaper imported corn for animal feed, millers may lean more heavily on non GMO sorghum as a substitute, a shift that could raise costs across poultry and dairy production later in the year.
Demand for corn is not expected to soften. The USDA holds its consumption forecast at 4.5 million tons, a reflection of how deeply white corn is built into the Kenyan diet through ugali and githeri. That steady demand is why the shortfall cannot be absorbed through belt tightening alone. It has to be imported, and imported fast.
The same weather system that scorched the Rift Valley is now squeezing the neighbours Kenya would normally lean on for grain, and forecasters expect that system to reverse hard in the coming months. Kenya’s food security still depends on rain it cannot control and imports it has yet to fully lock in, which means the months ahead will test both its supply chains and its patience.
